




About This Comparison
Our Editorial Standards
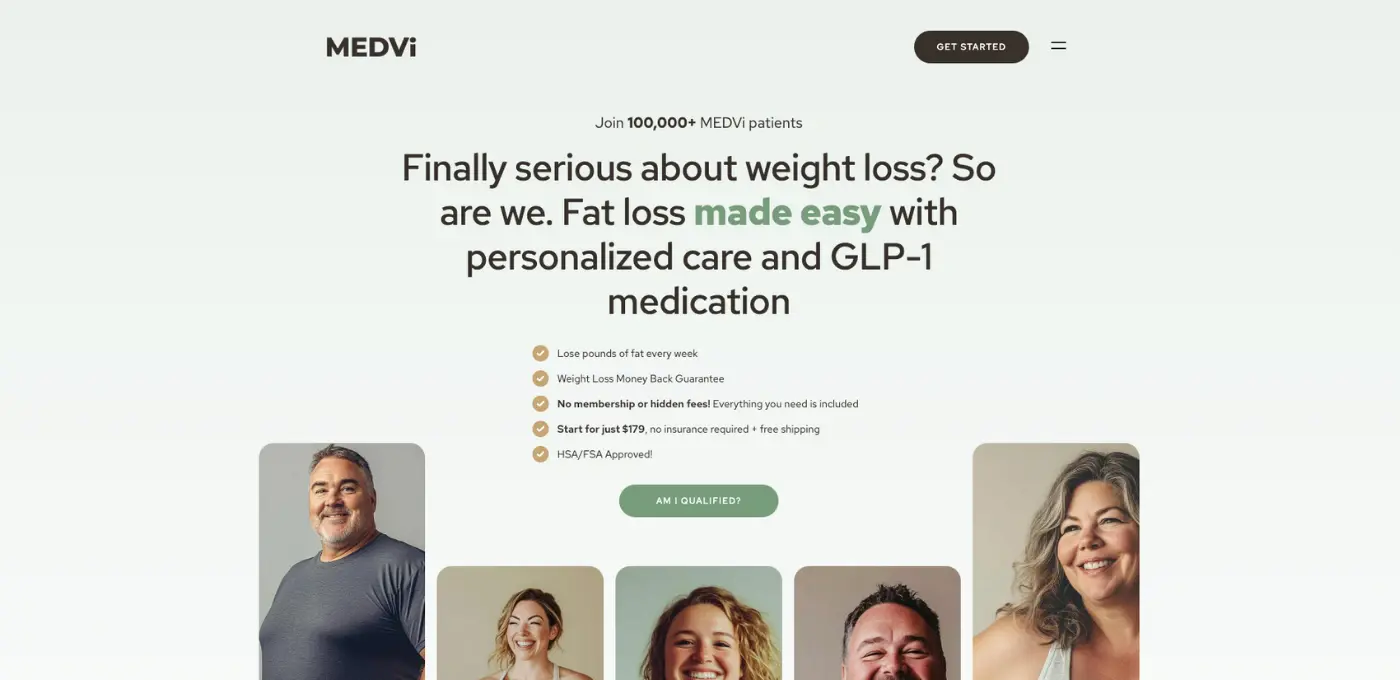
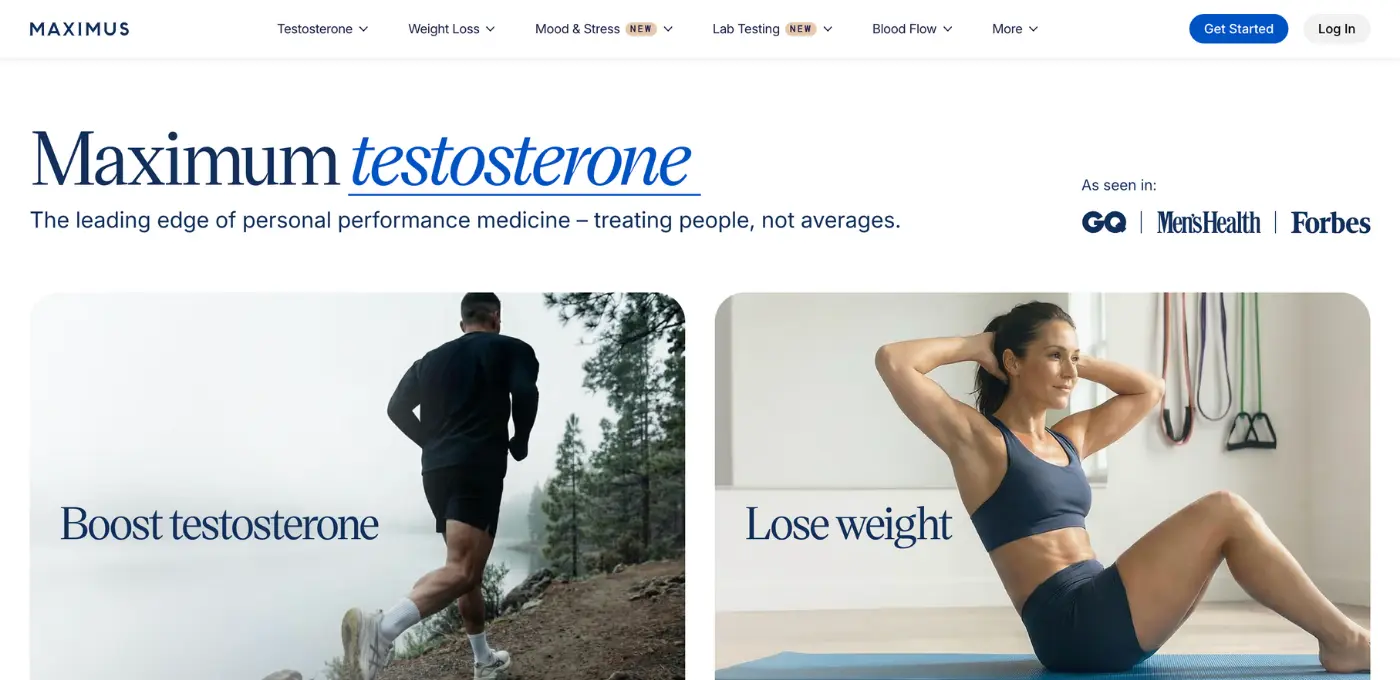
This medvi vs maximus provider comparison is independently researched by our editorial team. We compare telehealth services based on publicly available information including pricing, available treatments, and service areas. Our ratings are editorial judgments, not tallies of reviews.
Not Medical Advice: This comparison is for informational purposes only. We are not healthcare providers. Always consult with a licensed physician before starting any treatment. Read our full medical disclaimer and editorial policy.
MEDVi or Maximus: One Combination Formula Against the Cheapest Entry Price
Start with the number, because the number is most of the story. Maximus lists ED plans from $35.99 a month and MEDVi lists its ED formula from $114.00 a month. That is roughly three times the price for a product that is built on a different idea: Maximus will sell you one prescription molecule at a time, each FDA-approved in its own right, while MEDVi sells a single compounded formula that puts four ingredients into one dose. Below the price, the two companies have one uncomfortable thing in common. Both are carrying an open FDA warning letter, for entirely different reasons.
Read the entry price carefully before you compare it
- Maximus: plans from $35.99/mo as of 2026-09-10. Sildenafil from $49.99/mo, tadalafil from $53.99/mo.
- MEDVi: from $114.00/mo as of 2026-09-06, for the Quad combination formula.
- Floor to floor: $78.01 a month. Named-medication to formula: about $60 a month.
- Unverified at both: renewal pricing after month one, refund terms, state coverage.
One drug at a time, or four in one dose
Two open FDA letters, about two different problems
HSA, FSA and the parts of each service you can actually check
- HSA and FSA: accepted at Maximus for ED. Not verified either way at MEDVi.
- Clinical review: board-certified doctors at Maximus; included consultation with a decision inside 24 hours at MEDVi.
- Shipping: free priority at Maximus; free rush in plain packaging at MEDVi.
- Not charged unless approved: stated by MEDVi, not stated by Maximus in our records.
How to pick, in one pass
How We Compared Medvi vs Maximus
Where these facts came from
Prices are read out of our own brand feature records and printed with the date we last verified each one. We publish the floor, meaning the lowest monthly figure a company lists for the category, and we never print a figure below it. Where a company's cheapest plan price and its cheapest named medication price differ, as they do at Maximus, we show both rather than letting the smaller number stand alone.
The two warning letters were read in the FDA's warning letter index by letter number, including whether a close-out letter exists. We report what each letter says the agency found. Where a company disputes a letter's premises, as MEDVi does, we print the dispute and say we could not verify it.
Three things we could not verify at either company: refund terms, state-by-state availability, and what the monthly price becomes after any introductory period. We have left those gaps open on the page instead of filling them.
Final Verdict: Medvi vs Maximus
The verdict
On price, Maximus. It is cheaper at every figure we can verify, by $78.01 a month at the floor and still about $60 a month comparing named medication to named formula, and it accepts HSA and FSA funds while we could not confirm that MEDVi does.
On product structure, also Maximus, for a reason that has nothing to do with money. It will sell you one prescription molecule that holds its own FDA approval, and it publishes who its ED line is not for. MEDVi's ED offer is a single compounded formula with four ingredients and no single-molecule alternative in our records, and we hold no suitability or exclusion list for it.
MEDVi's genuine advantages are narrower: the one-dose format if that is specifically what you want, and a stated policy of not charging you if you do not qualify. Both companies carry an open FDA warning letter citing misbranding, so neither gets to be the cautious choice on that score. Both also score 9.2 out of 10 with us, which is a reminder that our score is not the thing to decide on here. The price and the format are.
Frequently Asked Questions
Which is cheaper for ED, Maximus or MEDVi?
Maximus, by a wide margin. Plans start at $35.99 a month as of 2026-09-10 against MEDVi's $114.00 a month as of 2026-09-06, a difference of $78.01 at the floor. Even comparing MEDVi against the named Maximus medications rather than the entry plan, sildenafil from $49.99 and tadalafil from $53.99, Maximus is roughly $60 a month cheaper.
What does the $35.99 Maximus plan actually include?
Our records say only that plans start at $35.99 a month, and that the named medications are priced above that: sildenafil from $49.99 a month and tadalafil from $53.99 a month. So that is the entry price for a plan rather than a confirmed price for a specific prescription. We did not verify what is bundled at that level, and you should confirm it before you sign up rather than assume the lowest number is the medication price.
Can I get a single ED medication instead of a combination formula?
At Maximus, yes. It prescribes sildenafil and tadalafil as individual medications, and each of those is FDA-approved as a standalone drug. It also offers a compounded vardenafil plus tadalafil combination as a separate option. At MEDVi, the ED listing we hold is the Quad combination only, with no single-molecule alternative named. Which medication and strength suit you is a decision for the clinician who reviews your case.
Is MEDVi's four-in-one ED formula FDA-approved?
No. MEDVi describes Quad as compounded, and compounded formulas are not approved or reviewed by the FDA for safety, effectiveness or quality. Tadalafil, sildenafil and vardenafil hold individual FDA approvals as separate drugs. That is not the same as the four-ingredient formula holding one, and it does not hold one.
Does Maximus or MEDVi accept HSA or FSA funds?
Maximus accepts HSA and FSA funds for its ED line. For MEDVi we have no information either way, so we are not going to tell you it does or it does not. Ask MEDVi directly before you plan around it. If you have either account, this is one of the larger practical differences between the two.
Does an open FDA warning letter mean I should avoid these companies?
That is your call, and here is what the letters are and are not. Both are findings about how a company described its products in its own marketing, cited as misbranding under sections 502(a) and 502(bb) of the Federal Food, Drug, and Cosmetic Act. Neither is a product recall and neither concerns any individual order. Maximus received MARCS-CMS 730095 on June 8, 2026 and MEDVi received MARCS-CMS 721455 on February 20, 2026, and when we checked FDA's warning letter index on October 6, 2026 it listed no response letter and no close-out letter for either, so we treat both as open. What it tells you is that both companies have been told their own claims overstated what the FDA had approved.
Sources & References
Our comparisons are informed by official sources and regulatory guidelines. We encourage you to verify information with authoritative sources.
Editorial Note: Researched and edited by our editorial team. AI tools assist with initial research and drafting; all content is fact-checked and edited by humans before publication. Learn more about our editorial standards


